
Know your cash? Find your price
Enter the cash you have and the down-payment percent you want. We'll estimate the highest home price that cash can cover, including closing costs.
Know the price? Find the cash you need
Enter the home price and down-payment percent to see how much cash you need at closing.
Know both? Find your down-payment percent
Enter the home price and the cash you have to see what down-payment percentage that cash represents.
What is a down payment calculator?
A Down Payment Calculator shows how much cash you need to buy a home, or how much home your cash can buy. It has three modes: start from the cash you have, start from the home price, or enter both to see what percentage you would be putting down. Each mode also estimates closing costs, the loan amount and the monthly payment, so first-time buyers and movers can set a realistic savings goal.
How to use it
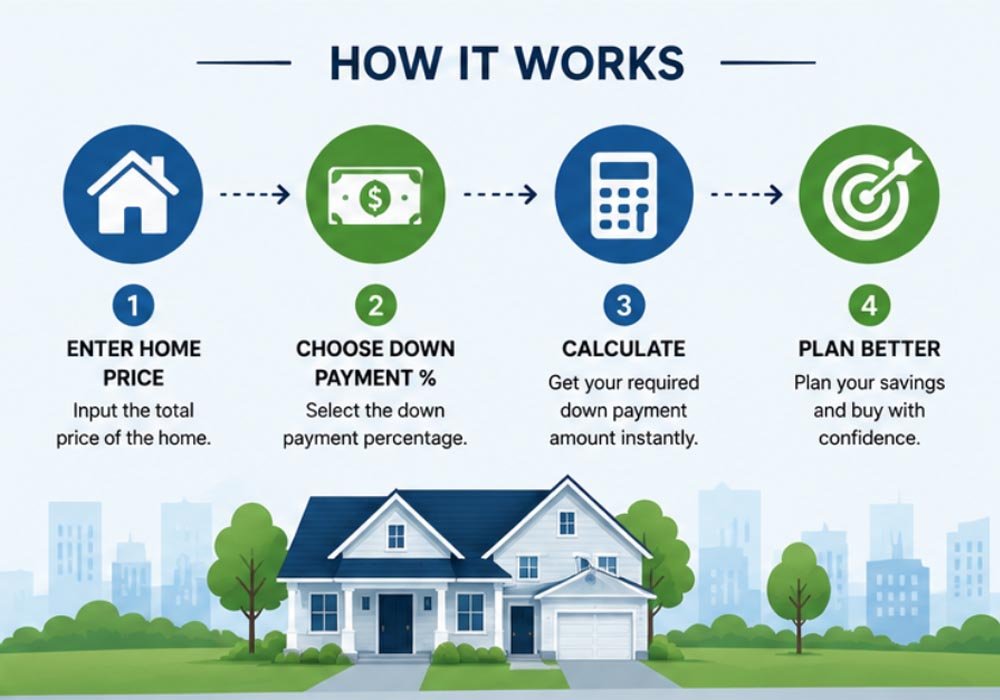
- Pick the box that matches what you already know (your cash, the price, or both).
- Enter the amounts and the down-payment percentage.
- Tick Include closing costs and enter them as a percent or a dollar amount.
- Enter the interest rate and loan term, then click Calculate.
Formulas
Down payment = Home price × Down-payment %
Cash needed = Down payment + Closing costs
Loan amount = Home price − Down payment
The monthly payment uses the standard loan formula M = P × r(1 + r)^n ÷ ((1 + r)^n − 1), where P is the loan amount, r is the monthly rate and n is the number of payments.
What Is a Down Payment?
A down payment is the portion of a home’s purchase price that a buyer pays upfront rather than financing through a mortgage. For example, a 10% down payment on a $300,000 home would be $30,000, leaving $270,000 to be financed through a mortgage before other costs. Down payments are commonly expressed as a percentage of the purchase price, and the amount required can vary depending on the mortgage program, lender, credit profile, and property type. A larger down payment generally means borrowing less money, while a smaller down payment allows buyers to purchase a home with less cash upfront.
Down Payment Requirements, Closing Costs, and Loan Options
Different mortgage programs have different down payment requirements, so buyers should consider both the upfront payment and other home-buying expenses. Common factors include:
- Conventional loans: Some conventional mortgages allow down payments below 20%, although a smaller down payment may require Private Mortgage Insurance (PMI).
- FHA loans: Qualified buyers may be able to purchase a home with a down payment as low as 3.5%, along with applicable mortgage insurance costs.
- VA loans: Eligible borrowers may qualify for VA financing with no down payment requirement in many situations.
- Closing costs: Buyers may also need money for appraisal fees, inspections, title-related expenses, lender charges, prepaid taxes, insurance, and other closing costs.
- Larger down payments: Putting more money down can reduce the mortgage balance and may lower interest costs and PMI expenses.
- Smaller down payments: A smaller upfront payment preserves more cash for emergencies, investments, home improvements, or other financial priorities.
Because requirements vary by lender and loan program, buyers should confirm current terms before making financial decisions.
Example
You are looking at a $300,000 home, plan to put 10% down and expect closing costs of about 3% of the price:
- Down payment: $300,000 × 10% = $30,000
- Closing costs: $300,000 × 3% = $9,000
- Cash needed at closing: $39,000
- Loan amount: $300,000 − $30,000 = $270,000
At 6.5% for 30 years, a $270,000 loan has a principal-and-interest payment of about $1,706.58 a month, before property tax, insurance and PMI.
Tips
- Save for closing costs and moving costs as well as the down payment.
- Keep an emergency fund; emptying your savings for a bigger down payment can leave you exposed.
- Compare 5%, 10% and 20% down in the calculator to see how the loan and payment change.
Frequently Asked Questions
A Down Payment Calculator is an online tool that calculates the amount of money required upfront based on a home’s purchase price and the selected down payment percentage. It can also show the remaining amount that may need to be financed.
The ideal down payment depends on your finances, mortgage program, and long-term goals. A larger down payment can reduce borrowing costs, while a smaller one may allow you to keep more cash available for other expenses.
No. A 20% down payment is not required for many mortgage programs. Some conventional loans allow lower down payments, while qualified FHA and VA borrowers may have other options.
Closing costs are expenses paid in addition to the down payment when completing a home purchase. They can include lender fees, appraisal charges, inspection costs, title services, taxes, insurance, and other transaction expenses.
Common sources include personal savings, eligible gift funds, down payment assistance programs, and certain retirement-related options when permitted by the applicable rules and plan requirements. Buyers should understand any restrictions or repayment obligations before using these funds.
Disclaimer: This calculator gives estimates for general information only. It is not financial, tax or legal advice. Results depend on the numbers you enter and on simplified assumptions, so your actual figures may differ. Check important decisions with a qualified professional or the official source.
Related Calculators
After you know how much cash you need, these calculators help you test the mortgage that goes with it.
Written by Sharp Calculator Team — we build and test every calculator on this site, checking each formula against hand-worked examples and official sources. Last updated: October 2026.