
You Can Afford a House Up To
$0
based on your income and expenses
| Loan Amount | $0 |
| Down Payment | $0 |
| Monthly Principal & Interest | $0 |
| Monthly Property Tax | $0 |
| Monthly Home Insurance | $0 |
| Monthly HOA | $0 |
| Total Monthly Payment | $0 |
Amortization Schedule
| Year | Interest | Principal | Balance |
|---|
Balance & Payments Over Time
Tracks remaining loan balance, cumulative interest paid, and cumulative total payment over the life of the loan.
What Is a House Affordability Calculator?
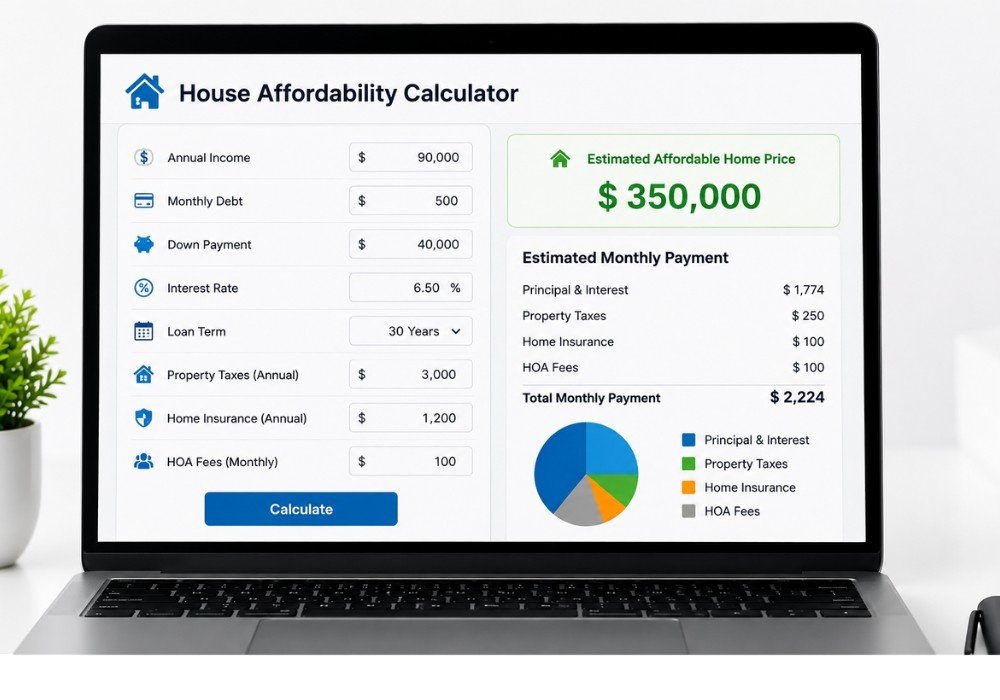
A House Affordability Calculator estimates how much home you can afford from your income, monthly debts, down payment, interest rate and loan term. It is useful for first-time buyers setting a budget, and for anyone who wants to check a price range before talking to a lender.
How to Use the House Affordability Calculator
Using the calculator takes about a minute.
- Choose a method: By Debt-to-Income (the calculator works out a safe payment from your income) or By Fixed Budget (you enter the monthly payment you want).
- Enter your annual household income before tax.
- Add your other monthly debt payments, such as car loans, student loans and credit card minimums.
- Enter your down payment.
- Enter the mortgage interest rate.
- Choose the loan term in years.
- Add estimated property tax, home insurance and any HOA fee.
- Pick a debt-to-income setting (conservative 28/36, aggressive 36/43, or your own).
- Click Calculate to see the highest home price that fits, your monthly payment breakdown and an amortization schedule.
House Affordability Formula
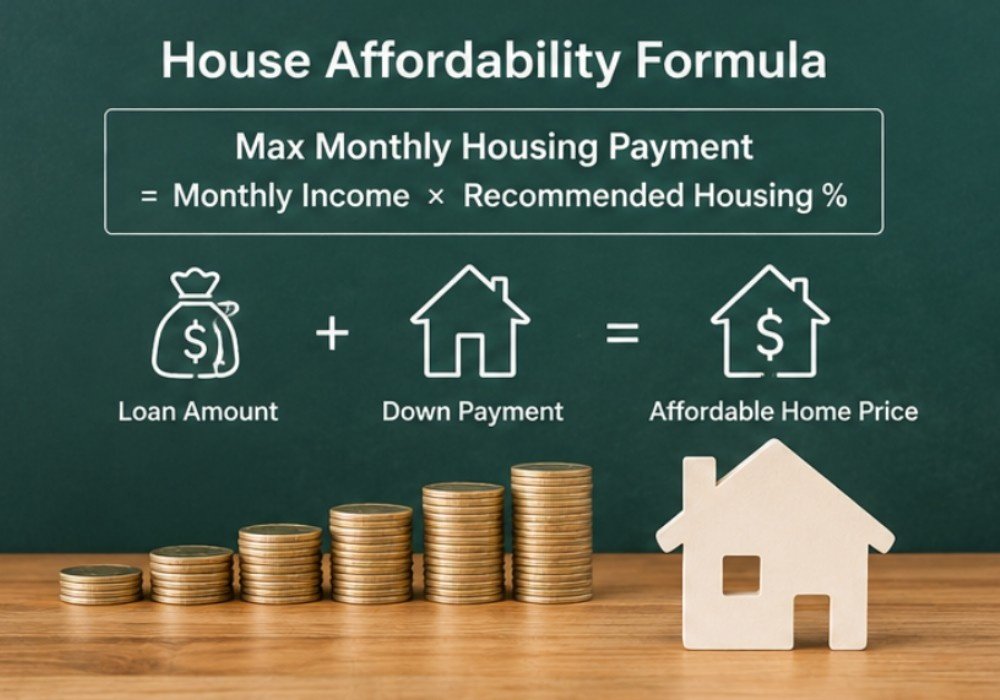
Lenders look mainly at your debt-to-income (DTI) ratio. The calculator applies two limits and uses whichever is lower:
- Front-end limit: maximum housing payment = monthly gross income × front-end ratio (for example 28%).
- Back-end limit: maximum housing payment = monthly gross income × back-end ratio (for example 36%) − your other monthly debts.
Property tax, insurance and HOA are taken out of that payment, and the rest is what is left for principal and interest (P&I). The loan that payment supports is:
Loan = P&I × ((1 + r)^n − 1) ÷ (r × (1 + r)^n)
where r is the monthly interest rate (annual rate ÷ 12) and n is the number of monthly payments. Finally:
Affordable home price = Loan + Down payment
Example Calculation
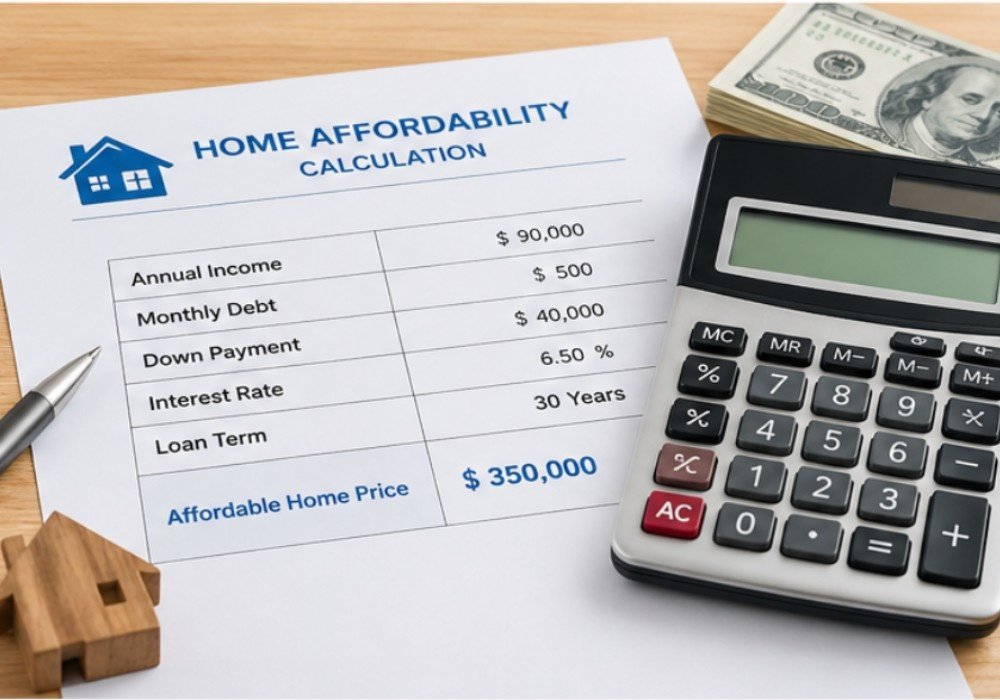
Suppose you earn $90,000 a year, pay $500 a month on other debts, have $40,000 for a down payment, and expect a 6.5%, 30-year fixed mortgage. Using the 28/36 rule:
- Monthly income: $90,000 ÷ 12 = $7,500.
- Front-end limit: 28% × $7,500 = $2,100 a month for housing.
- Back-end limit: 36% × $7,500 − $500 = $2,200, so the front-end limit of $2,100 applies.
- Assume about $400 a month for property tax and insurance. That leaves $1,700 for principal and interest.
- At 6.5% over 30 years, $1,700 a month supports a loan of about $269,000.
- Add the $40,000 down payment: an affordable price of about $309,000.
If you ignored taxes and insurance, the same income would seem to support about $372,000. That gap is why it matters to include every housing cost.
Tips before you shop
- Being approved for a loan is not the same as being comfortable with the payment. Leave room for savings, repairs and other goals.
- Get a local estimate of property tax and insurance; they vary widely by state and county.
- Keep an emergency fund in addition to your down payment and closing costs.
- Lower debts or a larger down payment raise the price you can afford more safely than stretching the loan term.
Frequently Asked Questions
A House Affordability Calculator estimates the maximum home price you can afford based on your income, monthly debts, down payment, loan term, and mortgage interest rate. It helps buyers set a realistic budget before purchasing a home.
The calculator provides a reliable estimate using the information you enter. Actual mortgage approval depends on your credit score, lender policies, debt-to-income ratio, and other financial factors.
Yes. If you enter property taxes, homeowners insurance, and HOA fees, the calculator includes them when estimating your monthly housing costs and affordable home price.
Absolutely. It’s designed for both first-time and experienced homebuyers who want to estimate how much house they can comfortably afford before applying for a mortgage.
No. The calculator provides an estimate for planning purposes only. Final approval depends on your lender’s underwriting process, credit history, income verification, and other financial requirements.
Disclaimer: This calculator gives estimates for general information only. It is not financial, tax or legal advice. Results depend on the numbers you enter and on simplified assumptions, so your actual figures may differ. Check important decisions with a qualified professional or the official source.
Related Calculators
Once you know your budget, these calculators help you plan the loan itself and compare your options.
Written by Sharp Calculator Team — we build and test every calculator on this site, checking each formula against hand-worked examples and official sources. Last updated: October 2026.